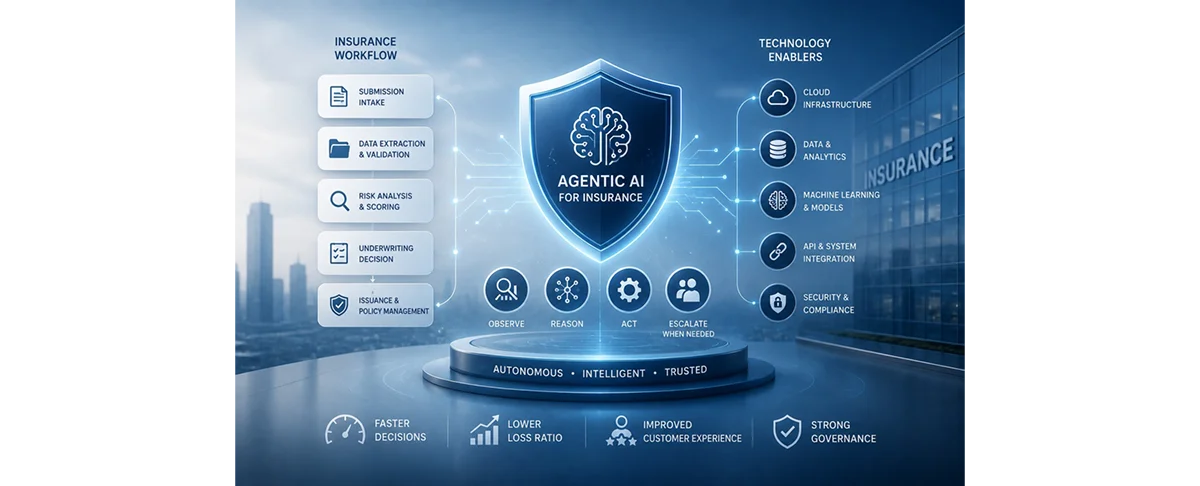
Why the Next Generation of Underwriting AI Won’t Be a Model It Will Be an Agent
For thirty years, insurance underwriting has been conquered by prediction models. The next thirty years will belong to a fundamentally different architecture.
By Dr. Anand R Fadte
CTO – Aviantos | 25th August 2026
For three decades, insurance underwriting has been quietly conquered by machine learning. Generalised linear models displaced actuarial tables in the 1990s. Gradient-boosted trees displaced GLMs in the 2010s. Deep learning arrived shortly after. Each generation squeezed another few percentage points out of the loss ratio, and each generation was, at its core, the same thing: a prediction function that took an application in and returned a risk score out.
That era is ending. And what replaces it is not a better model — it is a different kind of software altogether.
The Prediction Plateau
Talk to the chief underwriting officer of almost any major carrier and you will hear a version of the same story. The prediction models are good — very good. On structured data, accuracy has plateaued somewhere between 82% and 90% for most lines of business. Getting from 88% to 89% now costs a data-science team six months and a seven-figure budget. Loss ratios across the industry have compressed to within basis points of each other. The market has, in effect, hit the ceiling of what a model can do when the model’s only job is to predict.
The next few percentage points are not hiding in a better algorithm. They are hiding in a different architecture entirely.
What “Agent” Actually Means
The word “agent” has been badly overused in the last two years, so let me be precise. An agent is not a chatbot. It is not a large language model with a friendly wrapper. In the technical sense that matters for insurance, an agent is a system that:
- Receives a goal, not a prompt.
- Plans a sequence of steps to achieve that goal.
- Invokes external tools — a rulebook, a rating table, a risk model, a claims database — as part of that plan.
- Observes the output of each tool and updates its plan accordingly.
- Produces a decision with an explanation that is traceable to each step it took.
A prediction model asks: what is the risk of this applicant? An agent asks: what is the right decision for this applicant, given the rules, the risk table, the product catalogue, the historical precedent, and the confidence I have in each of those inputs?
That is a fundamentally different computational shape. And it is what the next generation of underwriting AI is being built around.
Three Capabilities Agents Unlock That Models Cannot
Reasoning across sources.
A prediction model sees one input space — the fields on the application. An agent can, mid-decision, retrieve the current version of a regulatory circular, look up an actuarial risk factor, pull the applicant’s prior policy history, and cross-reference all three. Complex cases that used to require a senior underwriter can now be assembled by the agent and handed to that underwriter fully cited.
Explainability by construction.
The single largest complaint against machine-learning underwriting has always been explainability. A gradient-boosted tree gives you SHAP values; an agent gives you an audit trail. When an agent recommends a conditional accept, the reason is not a feature-importance chart — it is a numbered list: rule R-04 applied, risk factor RF-12 triggered a 15% loading, prior claim in policy year 2024 flagged. Regulators globally — EIOPA in Europe, the PRA in the UK, NAIC in the United States, MAS in Singapore — are converging on precisely this kind of provenance requirement.
Self-supervision and confidence gating.
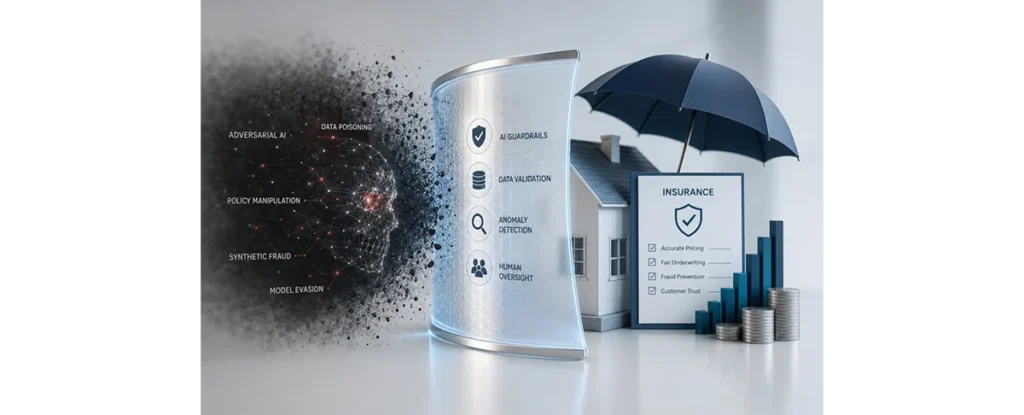
This is the least appreciated shift. A prediction model does not know when it is wrong. An agent, properly designed, produces a confidence score, evaluates its own reasoning, and — critically — escalates to a second-pass verification when its own confidence drops below a threshold. Recent work on confidence-gated adversarial critique has shown that this selective self-verification catches most otherwise-hallucinated conclusions at less than a tenth of the computational cost of verifying everything. For insurers whose margins are measured in basis points, that cost differential is the difference between a viable deployment and a research demo.
The Shift Is Already in Production
This is not a future-looking essay. The shift is already visible in production. Progressive has deployed agent-style architectures in parts of its auto underwriting stack. Ki, the Lloyd’s-market algorithmic syndicate, has effectively built its entire business around one. Lemonade has publicly credited its Maya and AI Jim agents with sub-two-second quote-to-bind for standard homeowners applications. And reinsurers including Munich Re and Swiss Re now offer “AI risk” cover for carriers deploying agentic systems — an implicit acknowledgement that this architecture is arriving whether the industry is ready or not.
What This Does Not Mean
None of this is a promise of full autonomy. Every serious deployment I know of keeps a human underwriter in the loop for the final decision, and every serious regulator requires it. What the agent architecture does is compress the underwriter’s job from evaluation to authorisation. The underwriter reviews a fully cited recommendation in thirty seconds instead of building the case from scratch over three days. That is a productivity gain of two to three orders of magnitude, and it is happening now.
The Strategic Implication
The carriers that will win the next five years are not the ones with the biggest data-science teams. They are the ones who understand that they are no longer buying prediction models — they are architecting decision systems. The build-versus-buy conversation changes. The vendor conversation changes. The regulatory conversation changes. Even the org chart changes: the chief data officer of 2020 becomes the chief AI officer of 2028, and the underwriting function begins to look less like a factory and more like a control tower.
The prediction era gave insurers accuracy. The agent era will give them speed, scale, and decisions that can be defended line by line to a regulator, a broker, or a customer. It is not a marginal improvement on the last thirty years of insurance AI. It is a different thing entirely.
— — —
About the author
Dr. Anand R. Fadte is Chief Technology Officer at Aviantos and a technology leader specializing in enterprise AI, Generative AI, agentic AI, and AI solution architecture. He writes on AI strategy, enterprise AI architecture, LLM applications, and responsible AI adoption, with a particular focus on regulated industries such as insurance, banking, and fintech. With 22+ years of global technology leadership experience and 40+ awards and recognitions, he brings a practitioner’s perspective to building and scaling AI solutions that deliver measurable business value.
Connect with him on
LinkedIn: linkedin.com/in/anandf-ai-head
Website: www.fadte.com